Why Is My Mortgage Credit Score Different From Credit Karma?
You checked your credit score online, felt good about the number — and then a mortgage lender pulled your credit and gave you something completely different. What happened?
You're not imagining it, and nothing went wrong. Mortgage credit scores are calculated differently than the scores you see on Credit Karma, your bank app, or most other free monitoring tools. And for home buyers in Jacksonville, FL and across Northeast Florida, understanding that difference can save you a lot of confusion — and help you walk into the mortgage process with realistic expectations.
Not All Credit Scores Are Built the Same
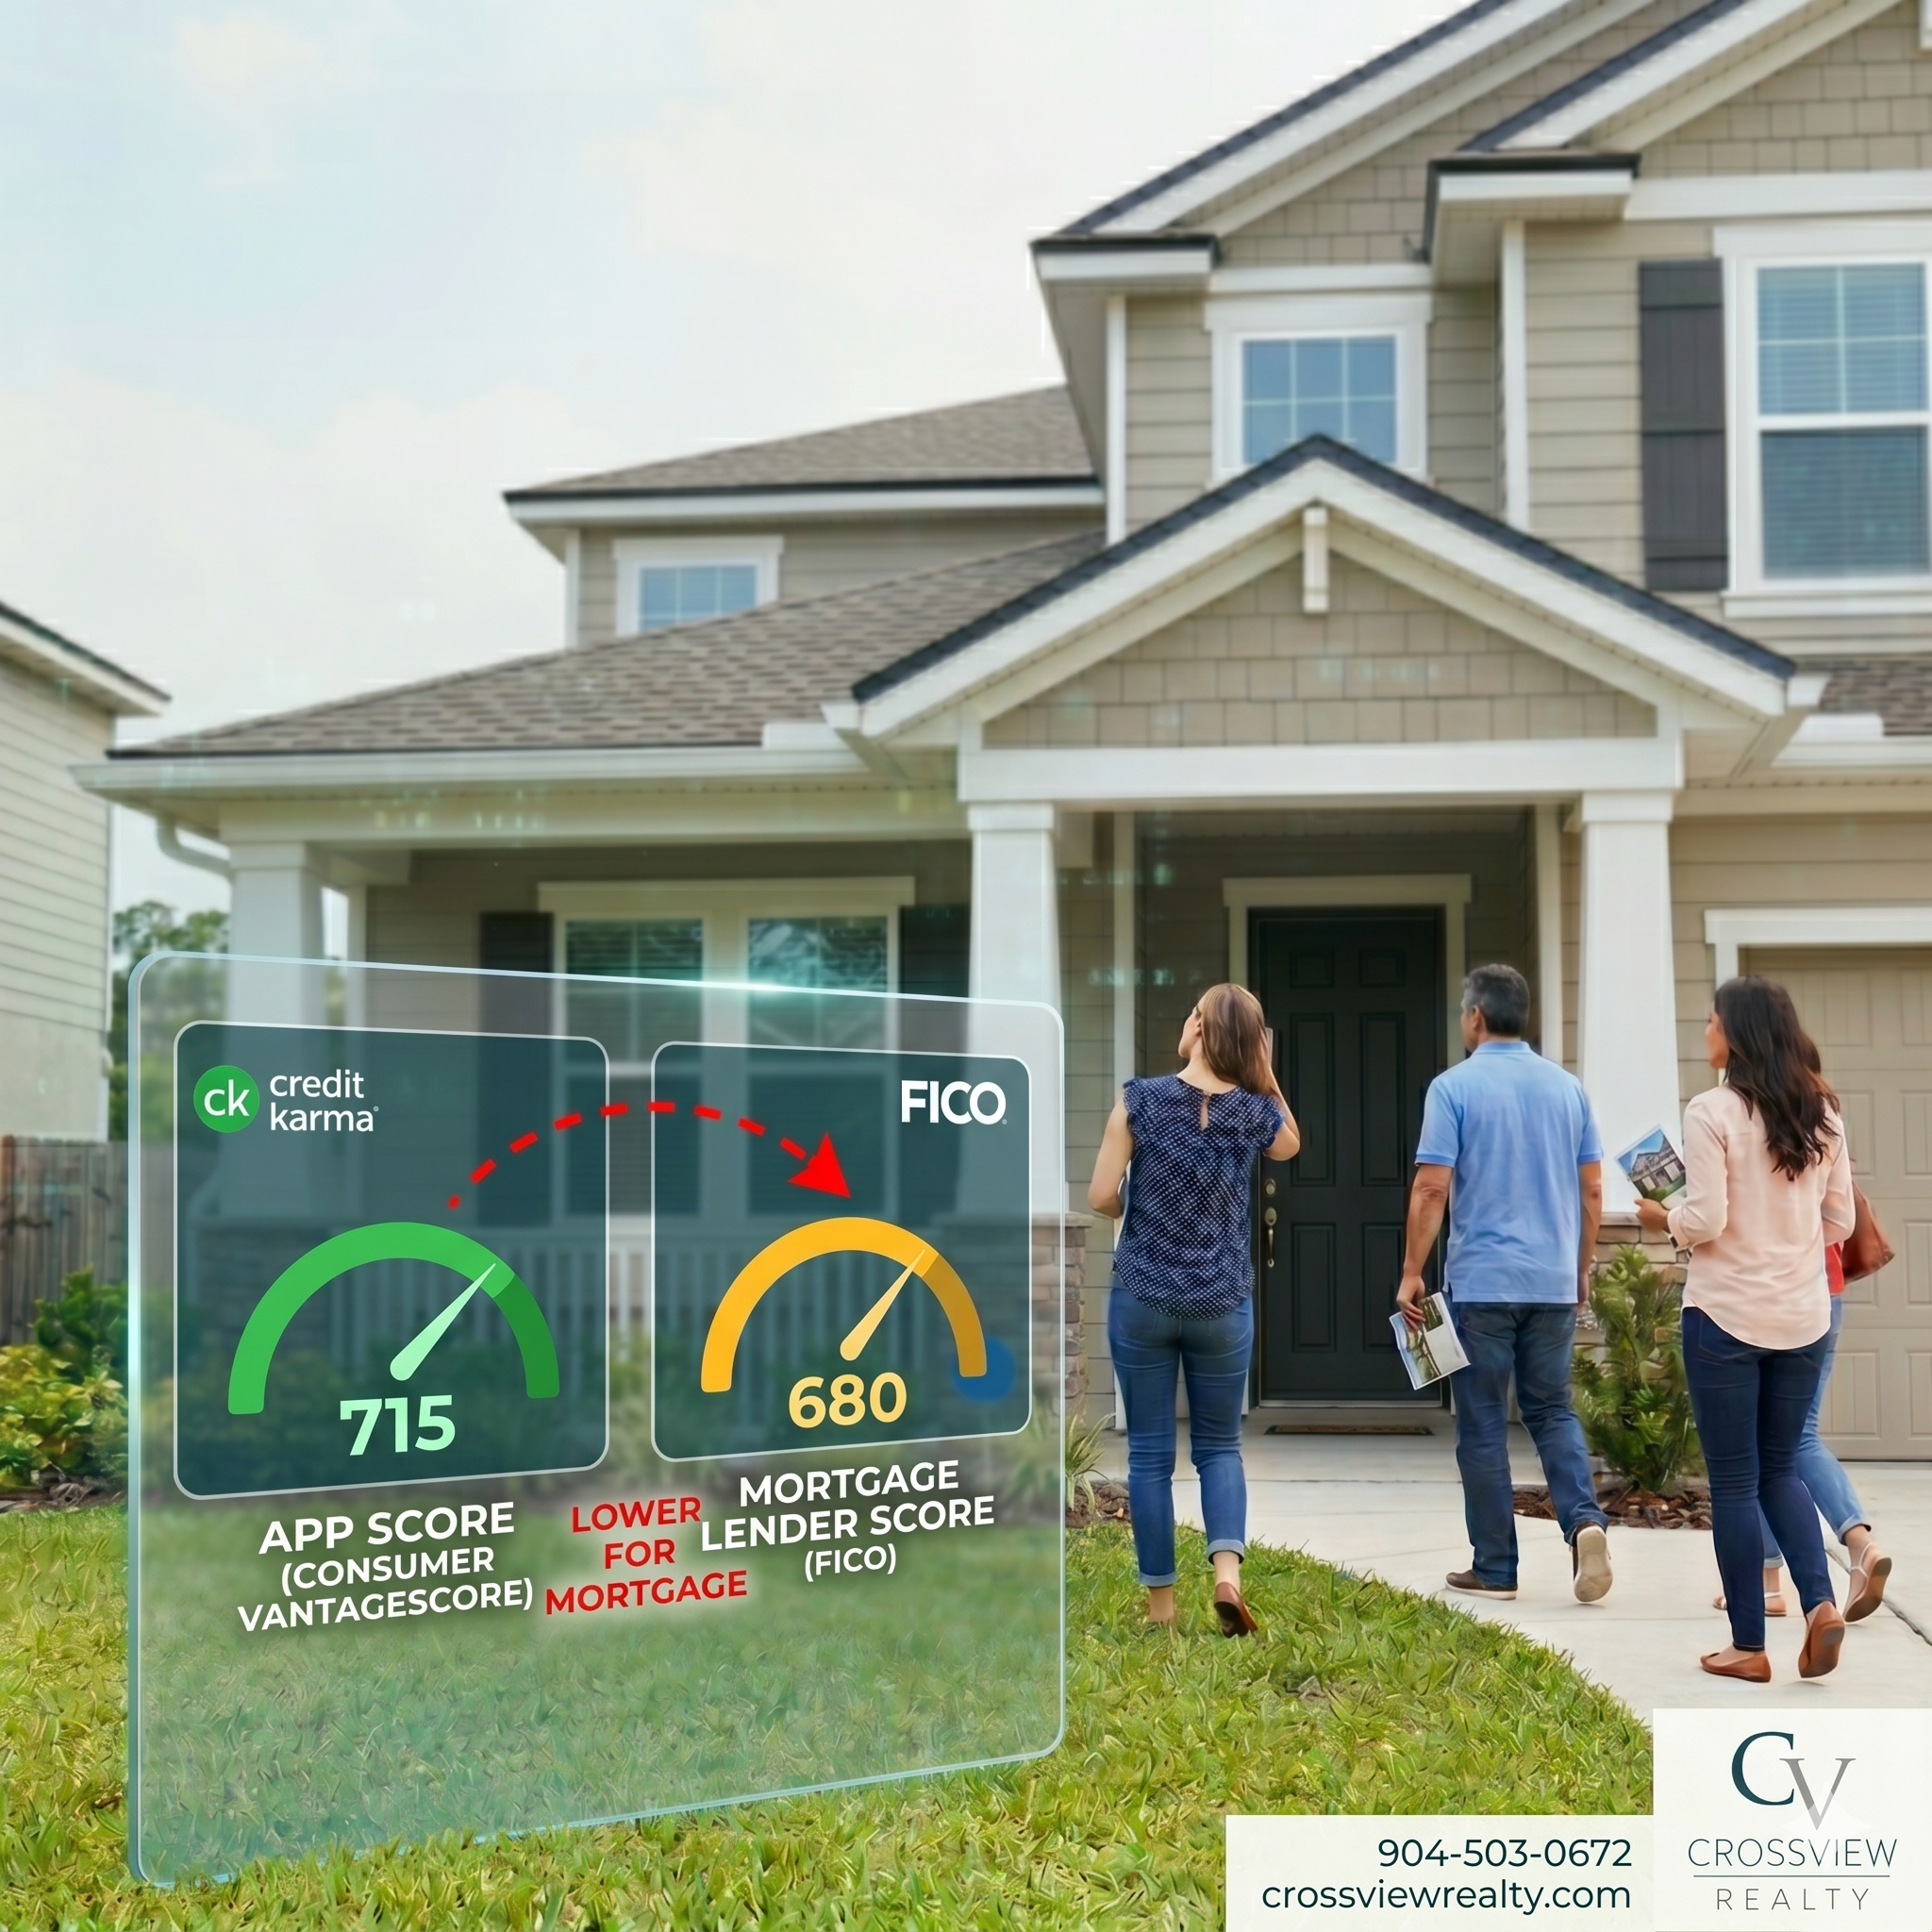
Here's the core of it: there's no single universal credit score. Different lenders use different scoring models depending on what they're lending for. When you check your score on Credit Karma, you're typically seeing a VantageScore — a model developed jointly by the three major credit bureaus. It's a solid general indicator of your credit health, but it isn't what mortgage lenders use.
Mortgage lenders are required to use specific FICO scoring models — and not just one. They pull all three bureaus (Equifax, Experian, and TransUnion) and typically use the middle of the three scores to qualify you for a loan. The FICO models used for mortgage lending are also older versions of the scoring algorithm, which weight certain factors differently than the models behind the scores you see day-to-day.
The result? Two legitimate credit scores, calculated from the same underlying credit data, that can land in noticeably different places.
Why the Mortgage Score Is Often Lower
This is the part that catches buyers off guard. In most cases — and this reflects what we consistently see with buyers we work with across the Jacksonville area — your mortgage credit score comes in lower than what you've been watching online.
The reason comes down to how each model weights your credit activity. Consumer-facing scores like those from Credit Karma are designed to give you a broad picture of your credit health. Mortgage scoring models are specifically calibrated to predict the risk of someone defaulting on a home loan — a much larger, longer-term financial commitment than a car loan or a credit card.
Because of that, mortgage models tend to place heavier emphasis on certain factors — like your history with installment loans, your overall debt load, and any derogatory marks — that may carry less weight in a general consumer score. The same credit file, evaluated through a different lens, produces a different number.
Don't Guess at What Will Help Your Score
This is where we see buyers make costly mistakes. It's tempting to Google "how to raise my credit score fast" and start making moves — paying down this card, opening that account, closing an old one. But what helps a consumer credit score doesn't always help a mortgage credit score. In fact, some of the most common DIY credit fixes can actually drop your mortgage score right when you need it most.
We've seen it happen. A buyer thinks they're doing the right thing, makes a few changes, and ends up in a worse position than where they started. Don't guess. It's not worth the risk when you're trying to qualify for a home.
The Right Move: Talk to a Lender First
If you're thinking about buying a home in Jacksonville, St. Augustine, Ponte Vedra Beach, or anywhere in Northeast Florida, the single best thing you can do before anything else is have a lender pull your actual mortgage credit score. Not Credit Karma. Not your bank app. A real mortgage pull.
From there, a good lender can tell you exactly where you stand, what loan programs you may qualify for, and — if your score needs work — specifically what to do to move the needle in the right direction for a mortgage. That last part is critical. The advice needs to be tailored to your file, not generic internet tips.
If you need a lender recommendation, we're happy to connect you with someone great. The right fit depends on your situation, and we work with lenders across Northeast Florida who know how to guide buyers at every credit level.
Ready to take the first step toward buying a home in Jacksonville, FL? Give CrossView Realty a call at 904-503-0672, email us at info@crossviewrealty.com, or visit crossviewrealty.com. We'll point you in the right direction — starting with the right lender.
Frequently Asked Questions
Q: Why is my mortgage credit score different from Credit Karma in Jacksonville, FL? Credit Karma uses a VantageScore model, while mortgage lenders use specific FICO scoring models required for home loan qualification. These models weight your credit activity differently, which is why the numbers often don't match — and why your mortgage score is frequently lower than what you see online.
Q: Will checking my credit score on Credit Karma hurt my mortgage application? No — checking your own score is considered a soft inquiry and doesn't affect any version of your credit score. However, when a mortgage lender pulls your credit, that's a hard inquiry, which can have a small, temporary impact. It's worth it to know exactly where you stand before you start shopping for a home.
Q: What should I do if my mortgage credit score is lower than I expected? Talk to your lender before making any changes to your credit. What helps a consumer score doesn't always help a mortgage score, and some common fixes can actually backfire. A good lender can review your specific file and tell you exactly what to address — and in what order — to move your score in the right direction.
Q: Should I try to raise my credit score before applying for a mortgage? Possibly — but only with guidance from a mortgage professional. Don't rely on general advice or self-help tips. Have a lender pull your mortgage credit score first, then follow their specific recommendations based on your actual file. If you need a lender referral in Northeast Florida, CrossView Realty is happy to connect you with someone who can help.